Attention: landlords
Free 20-minute live session
Pay off your home years soonerwith the rent you already collect
Most landlords use the rent to cover the rental, then pay their own mortgage with what's left after tax. Rental cash damming swaps those two around, with the same rent and the same bills.
▶ Watch this first, then save your seat below
Rental Cash Damming
Inside the cash-flow blueprint that pays off a $700K mortgage nearly a decade sooner, with the exact same monthly payment you're already making.
A cash-flow strategy Canadian landlords have used for decades.
Next live session: Wednesday evening · 20 minutes on Zoom · free, with Q&A
Register for the free session below
You'll get the Zoom link by email, plus a reminder before it starts.
Who should join
Landlords who want more from their rent
Your rent, on your home mortgage
Use the rent you already collect on the debt that costs you the most.
The rental's bills, still paid
Cover them with borrowing whose interest may be tax-deductible.
Basement suites and duplexes
It can work with a unit in your own home, not only a separate rental.
Your own numbers
See it modelled on your mortgage, your rent and your tax bracket.
How the money moves
Same rent. Different debt.
- Rent goes on your home mortgageThe rent you already collect becomes an extra payment on the debt that costs you the most.
- The room reopensWith a readvanceable mortgage, that payment comes back as room on a separate line of credit.
- The line pays the rental's billsMortgage, property tax, insurance and utilities. Interest on that borrowing may be tax-deductible.
- Repeat every monthYour home mortgage shrinks, and borrowing used for the rental takes its place.
Same rent, same bills. What changes is which debt you're paying down.
Before you register
This works best for:
- Landlords with a rental in their own name
- Real equity in your home
- A rental with steady rent
- A steady income
- Willing to keep simple monthly records
Probably not a fit: rentals held in a corporation; planning to sell the rental soon; your home mortgage is almost paid off; you couldn't carry the line if the unit sat empty for a few months.
What you'll learn
Inside the 20-minute session
- Why your home mortgage is the expensive debt, and your rental's borrowing isn'tTwo kinds of interest, treated very differently at tax time.
- The three moves that happen every monthRent onto your home mortgage, the room reopens, the line pays the bills.
- A worked example with a break-even rentalHow the home mortgage converts in about 9 years.
- What the CRA looks at, and the records that protect your deductionsThe setup is everything.
- Who it fits, and when it doesn'tIncluding corporations, vacancies and selling.
The example from the session
One rental. A very different payoff.
Illustrative only, not typical, not a guarantee, not a real client. Assumes a $400,000 home mortgage at about 4.5% with 25 years left, a rental bringing in $2,000 a month and costing about the same, and a 43% tax bracket.
Your host
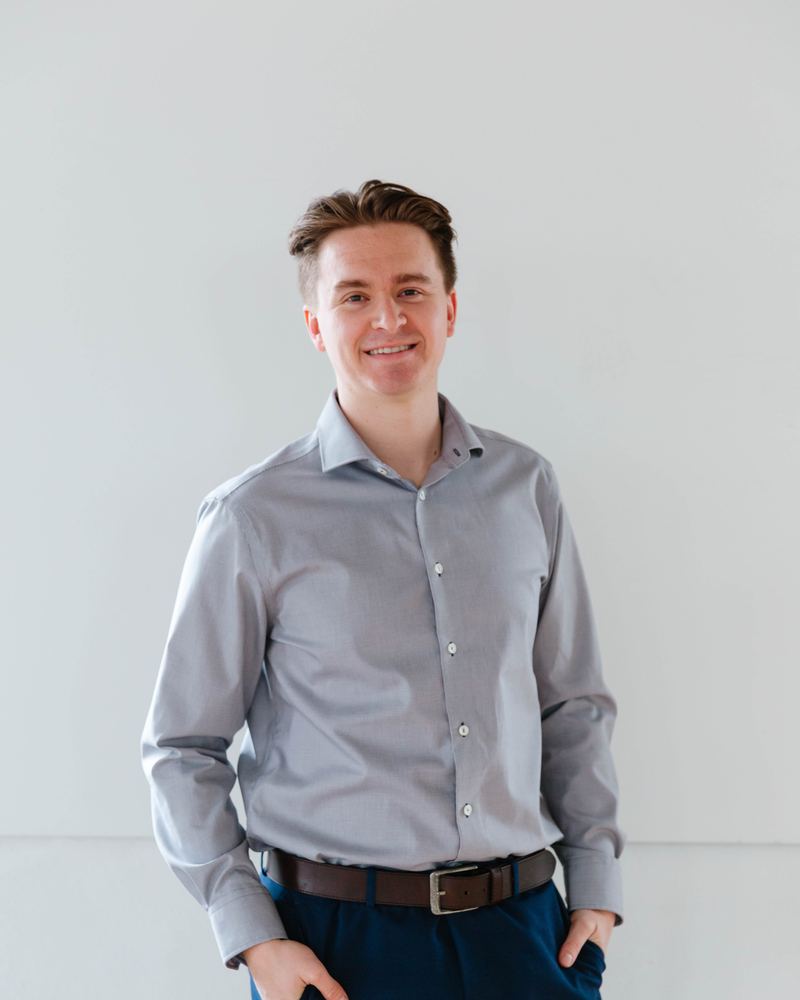
Jonah Hoyos
Most people are taught to chase the lowest rate. The bigger number is how your mortgage is structured.
I work in the mortgage industry, and I'll be honest: most Canadians are overpaying on their mortgage, and nobody tells them. We spend years in school and never learn how a mortgage actually works.
I run these strategies on my own home, and I've helped families across Canada save hundreds of thousands in interest. This session is the short version of what I wish every homeowner knew.
Make your mortgage work for you.
After you sign up
From the session to your own plan
- Step 1Watch the sessionTwenty minutes live on a Wednesday evening, or the recording whenever suits you.
- Step 2Book a callWe look at your own balance, rate and tax bracket and see what the strategy could do for you.
- Step 3Get it set upI arrange the right mortgage structure and show you how to run it month to month.
FAQ
Common questions
Is it really free?
Yes. It is a 20-minute teaching session, and nothing is sold at the end. If you want your own numbers afterwards, you can book a call.
Will there be a replay?
Yes. If you can't make it live, you can watch the recording of my free training anytime.
Is cash damming legal?
Yes. Interest on money borrowed to earn rental income may be deductible, and the CRA itself has used the term "cash damming". The setup and the records are what make it hold up, and you will confirm yours with your accountant.
Does it work if my rental loses money each month?
Often, yes. We cover positive, negative and break-even rentals in the session.
I already understand it. Can I skip ahead?
Yes. Book a call and we will look at your numbers directly.
Ready to put your rent to work?
Save a seat for a Wednesday evening. Twenty minutes on how the rent you already collect can pay your home off sooner.
Reserve my free seat →